August, 2026
The world has learned to speak about the global commons, but it has not yet learned how to govern them with the urgency, legitimacy and practical capacity they require. Climate stability, biodiversity, oceans, forests, the atmosphere and other shared planetary systems are affected by decisions that cross borders, markets and generations, while most governance tools remain trapped within national jurisdictions, fragmented negotiations and institutions that were not designed to respond quickly to planetary interdependence. In practice, there is no fully effective global governance system capable of protecting the global commons at the scale of the risks we now face.
This is not the first time humanity has faced a planetary problem that could not be solved by one country alone. The Montreal Protocol, adopted in 1987, is often recognized as one of the most successful environmental agreements in history. It created a global framework to phase out ozone-depleting substances, combining science, international law, public awareness, industry adaptation and political pressure. The Protocol shows that global coordination is possible when scientific evidence, public concern, consumer demand and institutional design converge around a clear planetary risk. It also shows that governance can evolve when societies understand that the cost of inaction is greater than the cost of transition.
Global Commons-Compliant Banking builds from that lesson but asks a different question: if political governance alone is not moving fast enough, could the financial system help create a practical governance layer for the global commons? The core idea is simple. Financial institutions could offer products and services that allow consumers, accountholders and businesses to align everyday financial transactions with the protection of shared planetary systems. The innovation would be to add a governance layer oriented toward the global commons, linking banking infrastructure, transaction flows, philanthropic allocation and legitimate decision-making mechanisms.
In the first phase, participating financial institutions could apply small transaction fees dedicated to global commons protection. These fees would not be designed as punishment, but as a practical way to generate recurring resources for philanthropic support to climate, biodiversity, forests, oceans, Indigenous peoples, territorial stewardship and other shared priorities. In a second phase, the system could evolve toward fee variability, in which different types of transactions or merchant categories would carry different fee levels depending on their relationship to global commons risks and impacts. The logic would not be punitive in a strict sense, but rather one of progressively internalizing risks and impacts that are currently often externalized onto society, territories and the planet. Consumer choice could drive adoption. If it were possible to make polluters pay more simply by switching banks, this could become attractive to conscious consumers.
 A legitimate mechanism would be needed to guide such a system. This is where the Global Commons Commission becomes relevant. The Commission describes its role as making policy recommendations and developing governance frameworks for the financial services industry to support responsible management of the global commons. Its working groups include Indigenous Peoples, civil society, scientific and academic experts, governments and the private sector, including financial service providers. It also refers to certifications and transaction fee recommendations based on customer and vendor histories, ISO 18245-compliant Merchant Category Codes and other verification mechanisms.
Such a body could bring together technical knowledge, civil society participation, voting by individual citizens on global referendums, scientific references, ethical safeguards and dialogue with financial institutions to guide decision-making parameters. It could represent a first-of-its-kind way to shift the power to govern transnational issues away from the exclusive domain of UN Security Council nation-state presidents and toward grassroots consumers and citizens. This would not replace public institutions or international law. Rather, it could complement them by creating a voluntary, financial and citizen-driven pathway for global governance experimentation.
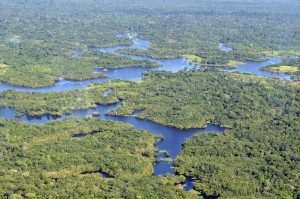 For the Amazon, this idea matters because the region is often treated as a global commons in discourse but not supported as one in practice. The forest provides climate regulation, biodiversity, cultural knowledge and water cycles that benefit the planet, yet the financial mechanisms available to Amazonian communities, Indigenous peoples, entrepreneurs and territorial organizations remain fragmented, insufficient and often poorly adapted to local realities. A Global Commons-Compliant Banking approach could help connect global consumers and financial institutions to the practical costs of protecting the systems from which they benefit.
The question now is not whether banking alone can govern the global commons. It cannot. The real question is whether banking can become one of the infrastructures through which citizens, consumers, financial institutions and philanthropic actors begin to share responsibility for planetary systems that current governance arrangements have failed to protect adequately. If designed with integrity, transparency and safeguards, Global Commons-Compliant Banking could become one way to move from symbolic concern to practical contribution, from abstract planetary responsibility to everyday financial choice, and from distant global governance debates to mechanisms that communities and institutions can test.
The Amazon Investor Coalition has become a signatory of the Global Commons Commission in order to help bring this new form of governance to scale.